Home-buying budget in Malaysia: five costs beyond the down payment
Published 17 October 2026
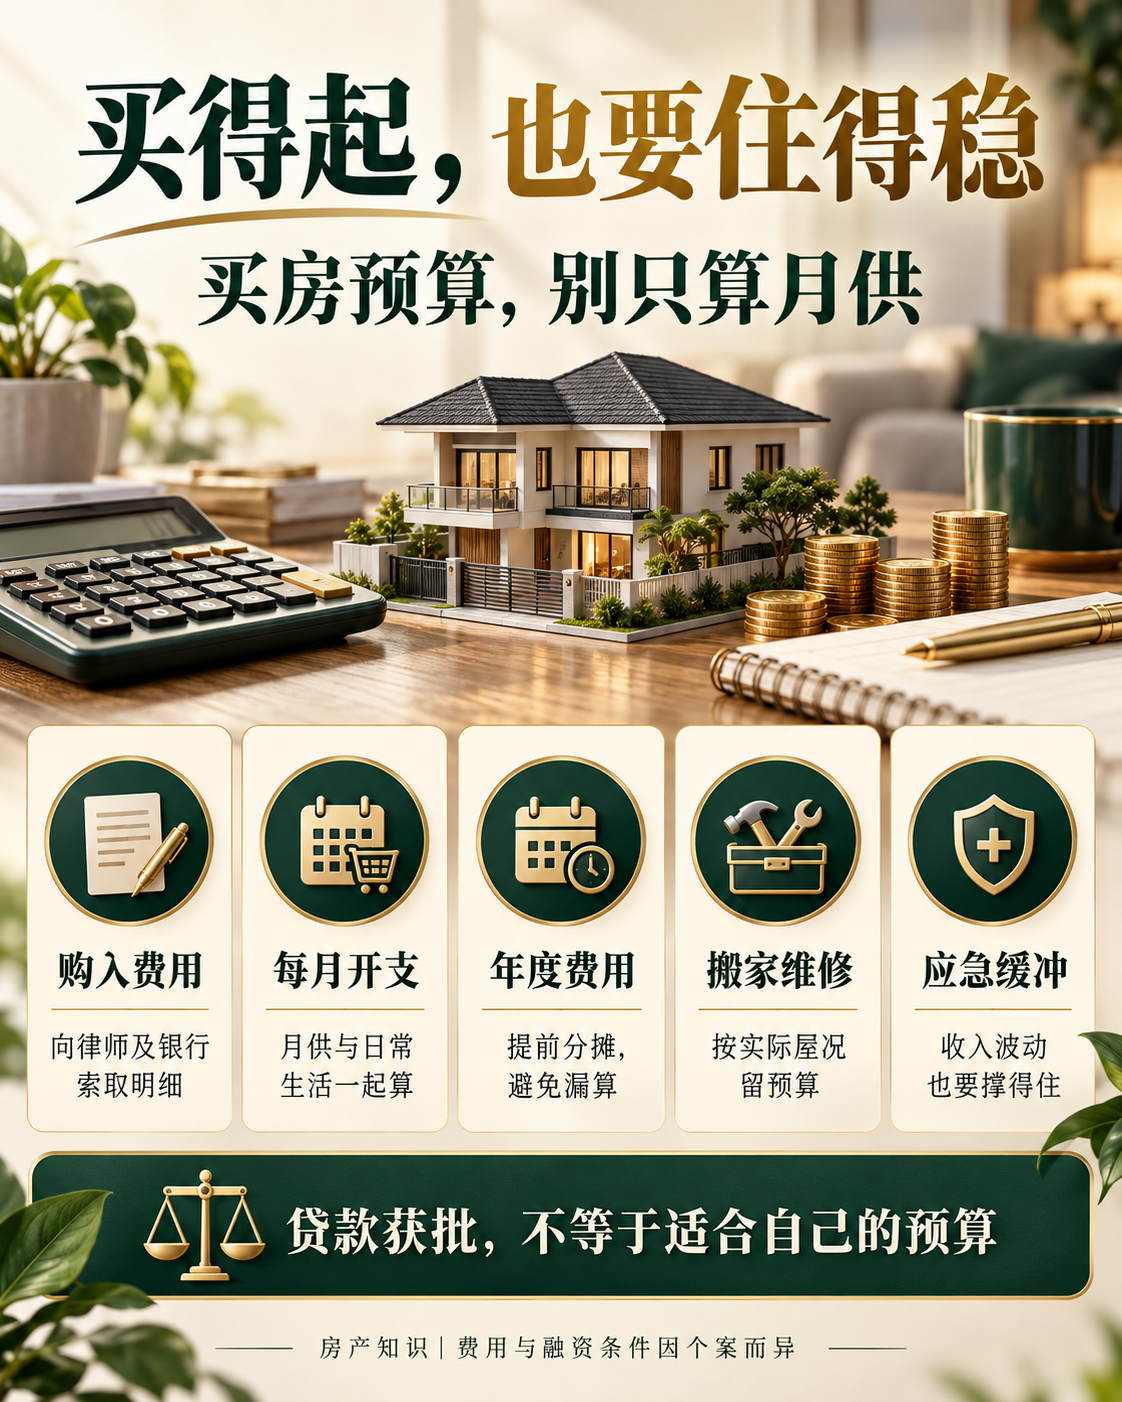
A useful home-buying budget covers more than a down payment and monthly instalment. Consider cash needed between signing and delivery, ordinary spending after moving in, and room to handle changes. This framework organises questions for your family, bank and lawyer; it does not set a universal income ratio or approval threshold.
1. Obtain an itemised purchase-cost estimate
Start with the expected purchase price, your own funds and confirmed financing arrangements. Ask your lawyer and bank about applicable sale and financing documentation costs, stamp duties, valuation and other expenses. Maybank's upfront-cost tool identifies such categories and advises checking final costs with the relevant parties.
For each item, record who pays, when it is due and whether it is confirmed or estimated. An advertised free-fee package may have conditions and exclusions. Do not assume every tax, disbursement or document is covered. Any exemption depends on actual eligibility, property and current requirements; another buyer's bill is not your quotation.
2. Include everyday monthly spending
List the proposed instalment alongside applicable management-related costs, utilities, internet, transport, insurance and household needs. Include existing commitments such as vehicle financing, education and family support. Comparing the instalment with salary alone can miss money already committed elsewhere.
Consider your present situation, a temporary income reduction and an increase in essential spending. This is a planning exercise, not a forecast. If there is no room left in any scenario, reassess the price range, timing or wider plan according to your circumstances. Approval by a bank is not a substitute for deciding what fits your own life.
3. Set aside annual and irregular bills
Applicable taxes, insurance and periodic charges may not arrive monthly. Once documents and bills are available, record amounts, due dates and responsibility, then decide whether to reserve money each month. Mark unknown items for confirmation rather than treating them as zero.
Also note major household bills unrelated to the home. They are not all property costs, but can fall due at the same time. Compare candidate homes using the same categories and period so the totals mean something.
4. Separate essential moving and repair work
Seek actual quotations for moving, cleaning, basic furniture, appliances and necessary repairs. Divide work into what is needed before occupation, what can follow later, and optional decoration. Where water ingress or electrical concerns exist, understand the cause and scope before relying on a low online estimate.
For packages, confirm quantities, models, delivery, installation and warranty. Do not count an unconfirmed gift as guaranteed savings or assume the seller has accepted repair costs. Ask your lawyer how delivery conditions and agreed repairs are recorded.
5. Retain accessible emergency funds
The appropriate buffer depends on income stability, responsibilities and actual spending. Check whether cash remains available after purchase for urgent repairs, family needs or a temporary interruption to income. With floating-rate financing, ask the bank how repayment could change; BNM explains that floating-rate borrowing costs can move with relevant interest-rate changes. Your actual arrangement depends on the product and documents.
Put timing into the worksheet
Use separate lines for purchase cash, signing-to-delivery payments, monthly spending and periodic reserves. Identify when money leaves the account, not only the final total. Loan calculators support comparison but their assumptions and outputs must be checked against formal financing information.
Plan a comfortable range before selecting a home. Contact us to discuss general budget, location and household needs without posting income records or account details publicly. This is general budget organisation, not individual financing, tax or legal advice.
Sources: Maybank upfront costs, BNM monetary policy information.
More articles
- How to check a REN in Malaysia: four steps before your property transaction
- Subsale home viewing checklist in Malaysia: five things beyond the renovation
- Maintenance fee vs sinking fund: three questions before buying a condominium
- How to choose a property location in Malaysia: a neighbourhood checklist